

Stripe Alternatives 2026 : Pick the One That Fixes Your Reason for Leaving
The best Stripe alternative depends on why you are leaving: Kurv if you sell small volumes and want no monthly fee, Helcim for lower fees, PaymentCloud for a restricted industry, Square for in-person selling, and Stax once volume makes a flat monthly fee cheaper than a percentage.
The best Stripe alternative depends on why you are leaving: Kurv if you sell small volumes and want… Show more
The best Stripe alternative depends on why you are leaving: Kurv if you sell small volumes and want no monthly fee, Helcim for lower fees, PaymentCloud for a restricted industry, Square for in-person selling, and Stax once volume makes a flat monthly fee cheaper than a percentage.
Starting from: 2.9%+30¢//transcation
Payments
- Integration capabilities
- Ease of use
- Numerous security features
- Diverse payment options
- High processing fees for disputes
- Geographical limitations

Starting from: $0/month
Flat Rate
- Reliable Merchant Services software
- Transparent transaction-based pricing
- Strong online payment solutions
- Responsive, knowledgeable support
- No money-back guarantee
- No free trial option

The best Stripe alternative depends on why you are leaving: Helcim for lower fees, Kurv if you take keyed or in-person cards at small volume and want one flat rate with no monthly fee, PaymentCloud for a restricted industry, Square for in-person selling, and Stax once volume makes a flat monthly fee cheaper than a percentage. Each of the Stripe competitors below is one Sonary reviews, matched to a specific reason for leaving. Stripe charges 2.9% + 30¢ per online card payment, 1.5% more on international cards, and $15 per dispute, per Stripe's own pricing page. Those numbers are fine for a new store. They start to hurt at volume, and they do not matter at all if your account is frozen.

When you're choosing a Merchant Services software, you want something that feels reliable, modern, and genuinely aligned with how you do business. KURV positions itself as a people-first platform… Read more
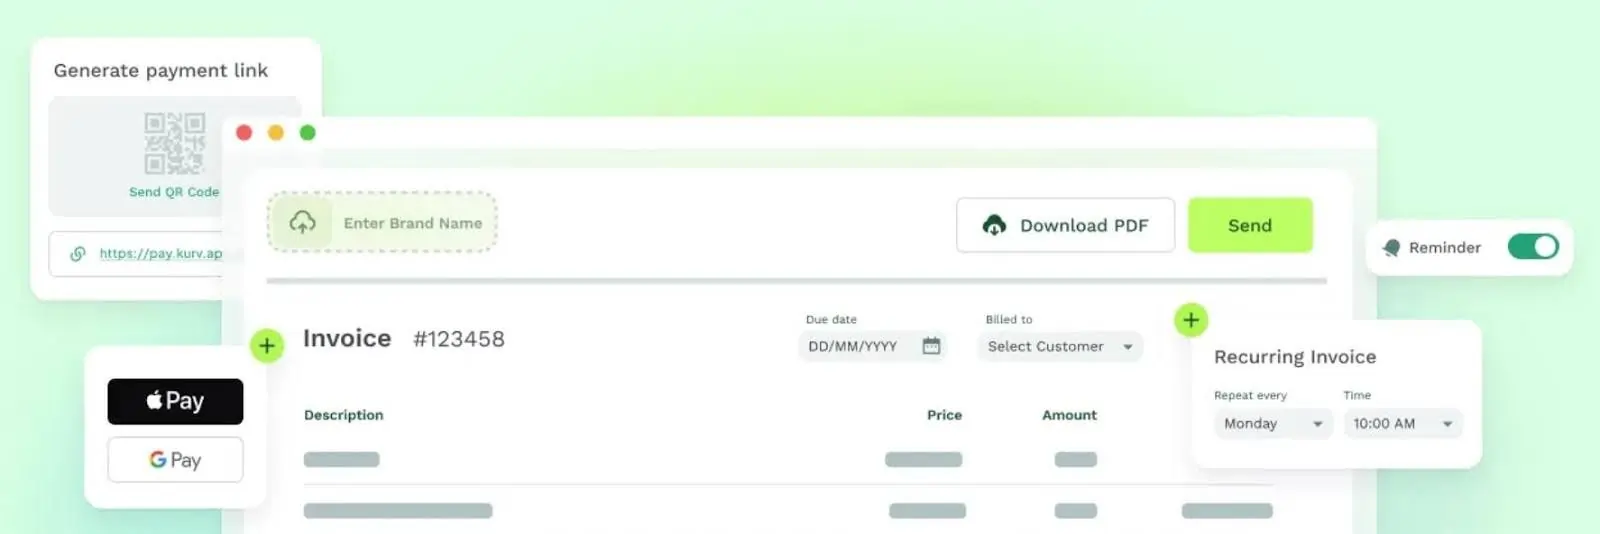
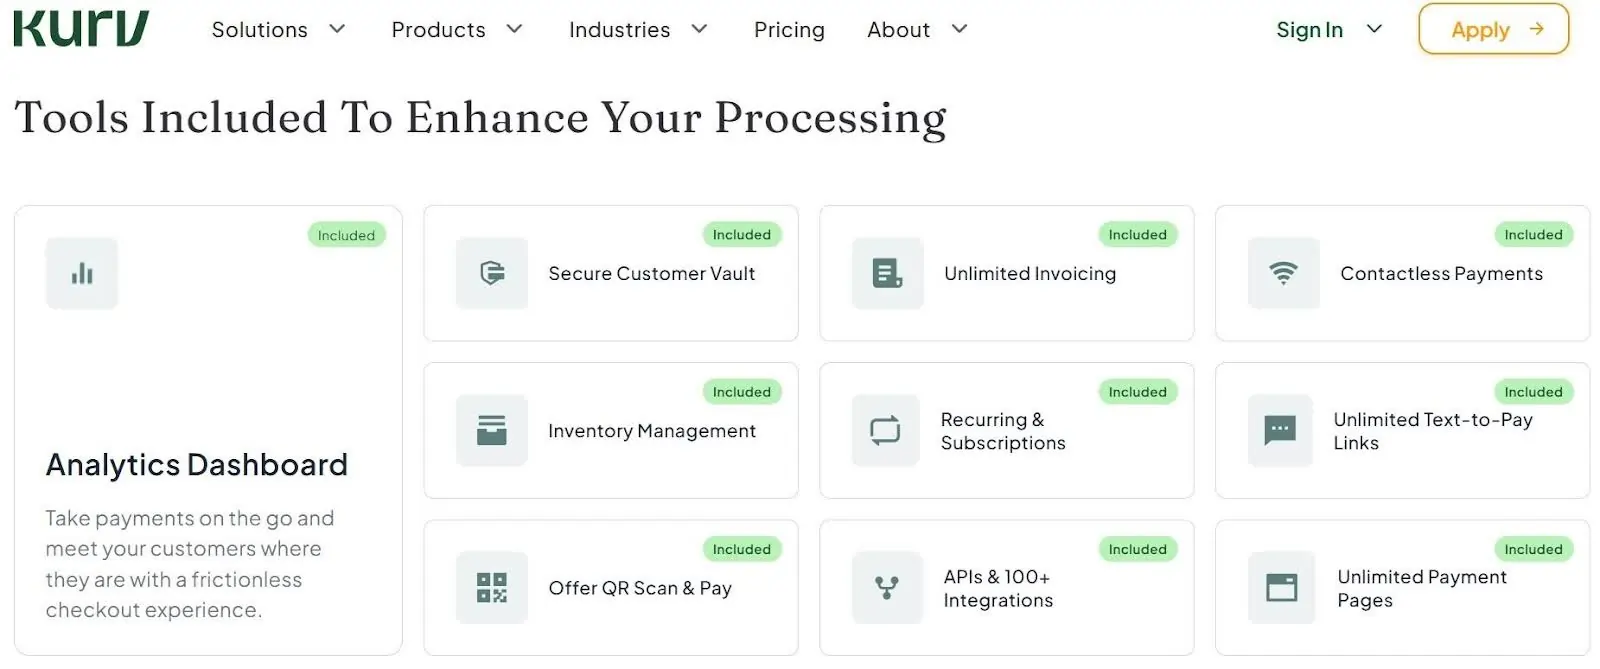
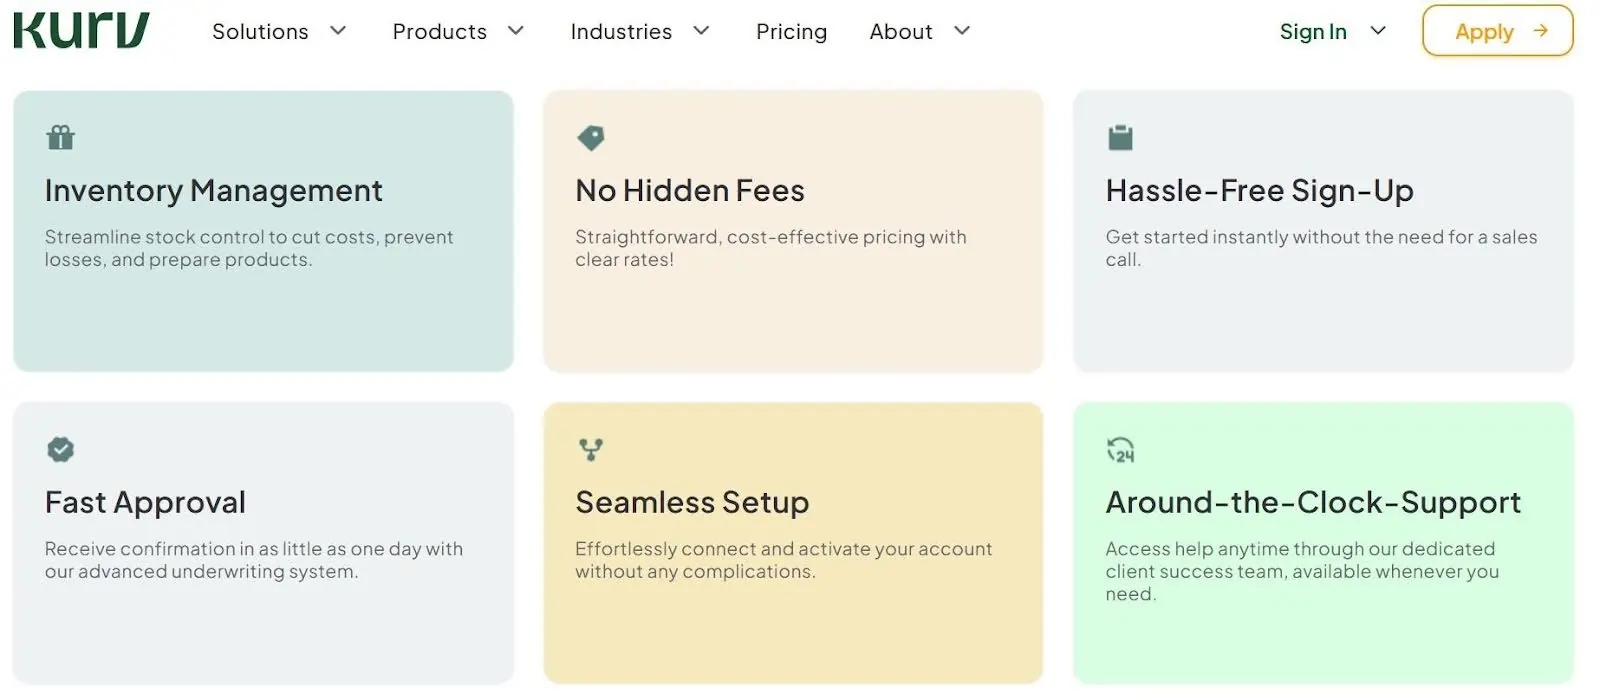
When you're choosing a Merchant Services software, you want something that feels reliable, modern, and genuinely aligned with how you do business. KURV positions itself as a people-first platform that simplifies managing online merchant services without sacrificing flexibility or performance.Using one connected ecosystem, you can access online payment platforms, payment gateway technology, and secure online payment processing services designed to grow with you. Kurv offers merchant services software that helps you manage online payment solutions, e-commerce payment methods, and in-person transactions from one streamlined dashboard.
Learn more in our full Kurv review.
Pros & Cons
- Reliable Merchant Services software
- Transparent transaction-based pricing
- Strong online payment solutions
- Responsive, knowledgeable support
- No money-back guarantee
- No free trial option
Features
- Tap to Pay
- Fraud Monitoring
- ACH Payment Processing
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- In-Person Payments
- Mobile Payments
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Fraud Prevention
- Payment Processing Services Integration
- Recurring Billing
- Reporting/Analytics
- iOS
- Android
- Cloud-Based
- Windows
- Mac
- Instore Sales
- Online Sales
- Mobile Sales
- Electronic Signature
- Multiple Payment Gateways
- Mobile Credit card processing
- Contactless NFC
- Mobile Card Reader
- Electronic Receipts
- 3rd-Party Integrations
Pricing
$0
mo/
month
$0
mo/
month
Screenshots



Helcim Merchant Software provides retail and e-commerce businesses with a reliable payment processing solution that simplifies transactions. It offers credit card processing, invoicing, a… Read more
Helcim Merchant Software provides retail and e-commerce businesses with a reliable payment processing solution that simplifies transactions. It offers credit card processing, invoicing, a Point-of-Sale (POS) system, e-commerce tools, and customer management features. With no monthly fees and an interchange-plus pricing model, businesses benefit from cost savings and automatic volume discounts. Helcim’s all-in-one platform supports online and in-person payments, making it ideal for growing businesses. Its user-friendly interface, security features, and integrated reporting help streamline operations. In this Helcim Merchant Software review, I'll discuss features, performance, customer service, and Helcim pricing.
Learn more in our full Helcim review.
Pros & Cons
- No minimum processing requirement
- Easily navigate surcharging, convenience fees, and service charge with one tool
- No monthly fees
- Excellent customer service
- Exclusive to low-risk industries
Features
- ACH Payment Processing
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- In-Person Payments
- Mobile Payments
- Multiple Payment Gateways
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Fraud Prevention
- Payment Processing Services Integration
- Recurring Billing
- Cash Transactions
- Contactless NFC
- Electronic Receipts
- Mobile Card Reader
- iOS
- Android
- Cloud-Based
- Windows
- Mac
- Instore Sales
- Online Sales
- Mobile Sales
Pricing
1.83%
+ 8¢/
+ 8¢
2.27%
+ 25¢/
+ 25¢

Stax is a merchant services provider that offers monthly membership pricing instead of percentage-based markups for payment processing. It provides useful features to complement its payment… Read more
Stax is a merchant services provider that offers monthly membership pricing instead of percentage-based markups for payment processing. It provides useful features to complement its payment processing services, such as its Omni Integrated Payments suite. Stax works well for high-volume businesses.
Learn more in our full Stax review.
Pros & Cons
- Quickbooks integration
- Transparent monthly pricing with no percentage markups
- Omni Integrated Payments platform
- US-based merchants only
- Pricy for low-volume businesses
Features
- ACH Payment Processing
- Billing & Invoicing
- Debit/Credit Card Processing
- Electronic Signature
- In-Person Payments
- Mobile Payments
- Online payment processing
- PCI Compliance
- POS Integration
- Recurring Billing
- Reporting/Analytics
- Electronic Receipts
- Mobile Card Reader
- iOS
- Android
- Cloud-Based
- Monthly subscription
- Instore Sales
- Online Sales
- Mobile Sales
Pricing
$99
mo/
month
$199
mo/
month
$199
mo/
month

PaymentCloud stands is a leading provider of merchant services, offering secure, scalable, and innovative payment solutions tailored to businesses of all sizes and risk levels. Renowned for their… Read more
PaymentCloud stands is a leading provider of merchant services, offering secure, scalable, and innovative payment solutions tailored to businesses of all sizes and risk levels. Renowned for their white-glove approach, PaymentCloud integrates state-of-the-art fraud prevention tools, advanced payment gateways, and seamless API connectivity with platforms like Shopify, Authorize.net, and NMI. Their services span from credit card and ACH processing to mobile and contactless payments, empowering businesses to accept payments anytime, anywhere. With a commitment to personalized service and cutting-edge technology, PaymentCloud ensures businesses can optimize their payment processes, safeguard against fraud, and scale effectively in today’s competitive market. In this review, I'll cover the PaymentCloud pricing structure, top features, performance, and more.
Learn more in our full PaymentCloud review.
Pros & Cons
- Works with high-risk merchants
- Free credit card terminal
- No account setup fees
- Pricing not publicly available
Features
- ACH Payment Processing
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- Electronic Signature
- In-Person Payments
- Mobile Payments
- Multiple Payment Gateways
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Fraud Prevention
- Payment Processing Services Integration
- Recurring Billing
- Reporting/Analytics
- Cash Transactions
- Contactless NFC
- Electronic Receipts
- Mobile Card Reader
- iOS
- Android
- Cloud-Based
- On-place Installation
- Windows
- Mac
- Monthly subscription
- Annual subscription
- Instore Sales
- Online Sales
- Mobile Sales

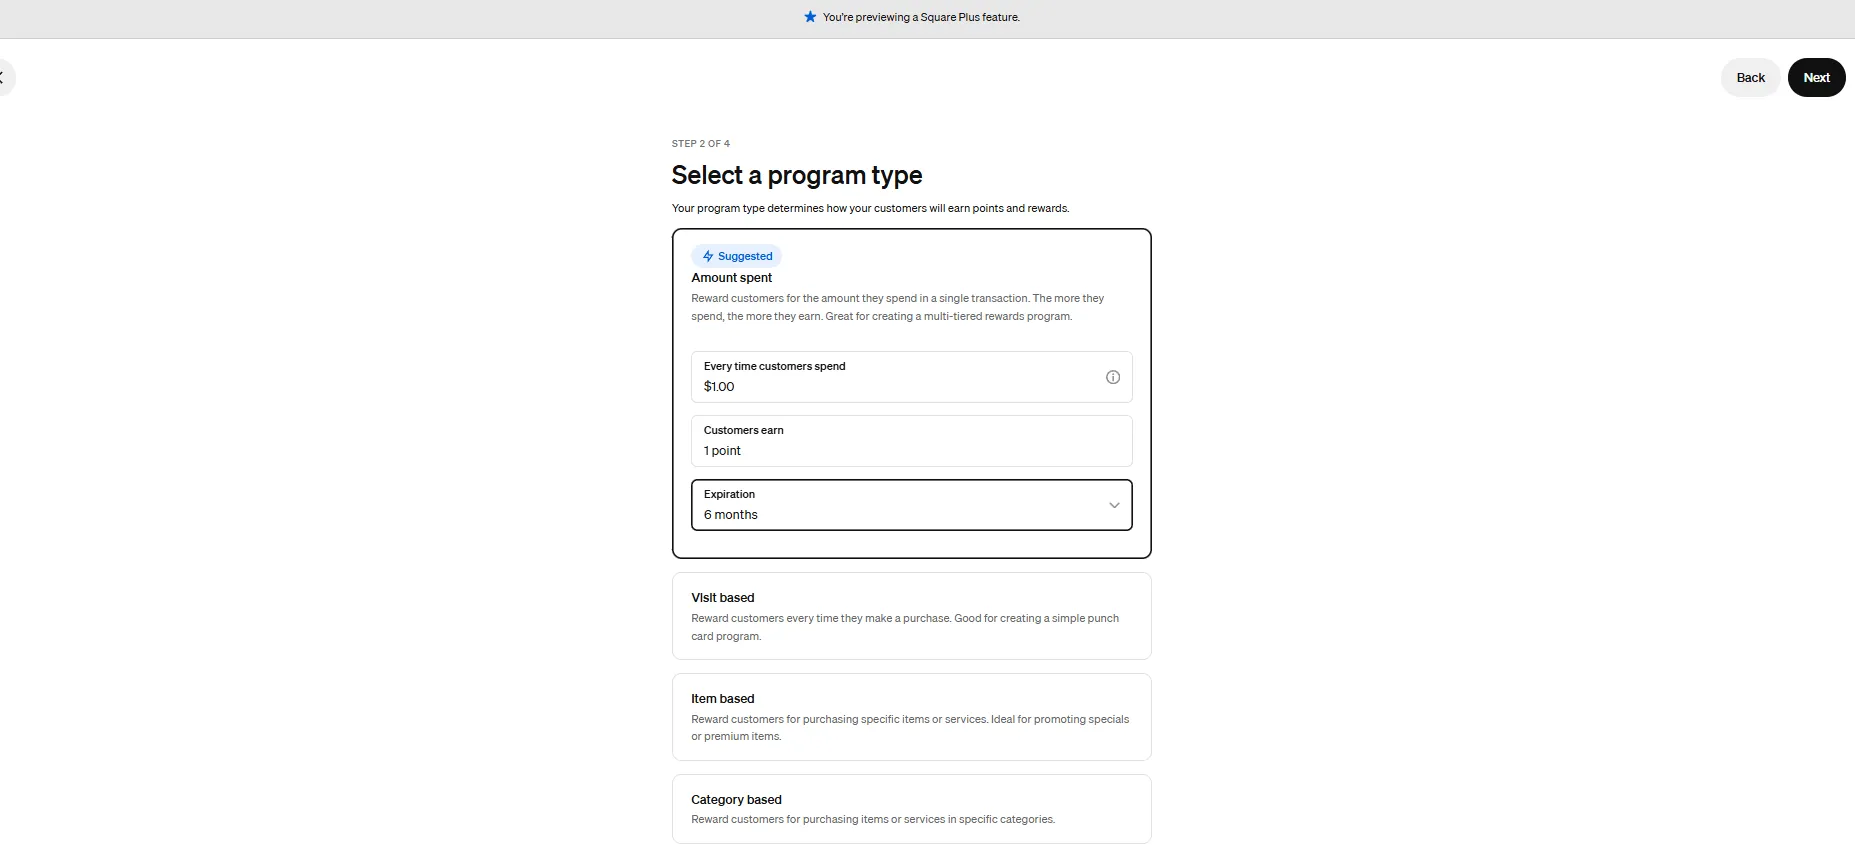
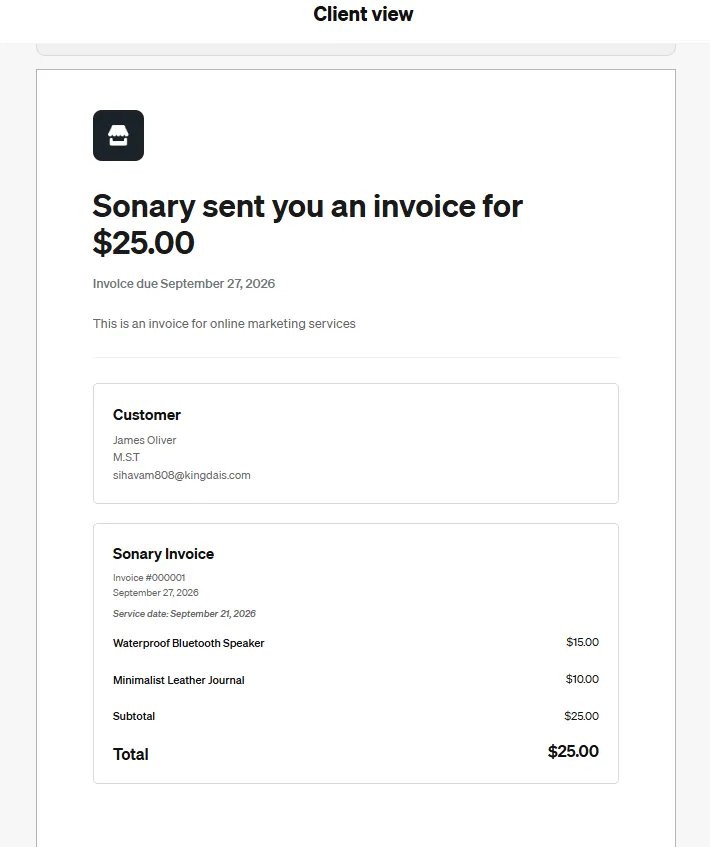
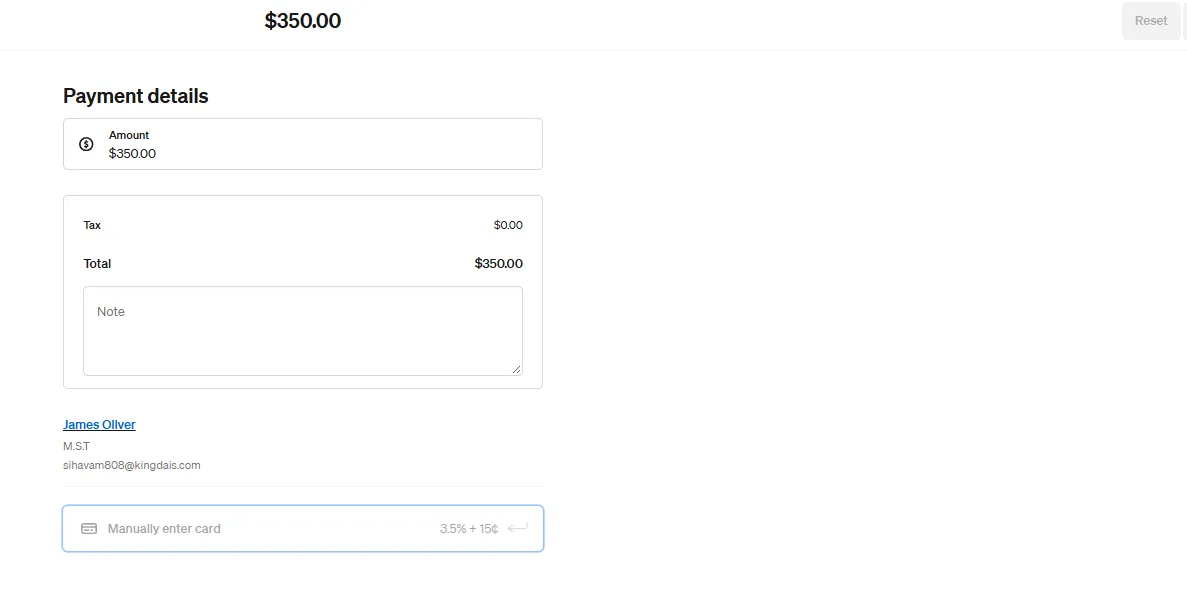
Square is a trailblazer in merchant services, powering over 4 million businesses globally with its comprehensive suite of payment and business management solutions. From seamless point-of-sale… Read more
Square is a trailblazer in merchant services, powering over 4 million businesses globally with its comprehensive suite of payment and business management solutions. From seamless point-of-sale systems to advanced software for payroll, marketing, and customer loyalty, Square enables businesses to operate efficiently and scale effortlessly. With user-friendly hardware, secure payment options, and integrated financial tools like Square Banking, it transforms how businesses manage their operations. Square's innovative approach, supported by powerful technology and unwavering reliability, provides unparalleled value to entrepreneurs and enterprises across diverse industries, making it an indispensable partner in business success. In this review, I'll dive into Square pricing, performance, features, and customer service.
Learn more in our full Square review.
Pros & Cons
- Affordable chip card readers
- Competitive transaction fees (especially for low-volume businesses)
- Omnichannel selling capabilities
- No time tracking
- No late fee capabilities
- Doesn’t support high-risk merchants
Features
- ACH Payment Processing
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- Electronic Signature
- In-Person Payments
- Mobile Payments
- Multiple Payment Gateways
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Fraud Prevention
- Payment Processing Services Integration
- Recurring Billing
- Reporting/Analytics
- Contactless NFC
- Electronic Receipts
- Mobile Card Reader
- iOS
- Android
- Cloud-Based
- On-place Installation
- Windows
- Mac
- Instore Sales
- Online Sales
- Mobile Sales
Pricing
$0
mo/
month
$29
mo/
month
Screenshots
PayPal Merchant Services is one of the most established online payment platforms, known for its ease of setup, global reach. For small and mid-sized businesses, PayPal offers a vast commerce… Read more
PayPal Merchant Services is one of the most established online payment platforms, known for its ease of setup, global reach. For small and mid-sized businesses, PayPal offers a vast commerce ecosystem that combines online payment processing, e-commerce integrations, and even in-person point-of-sale tools – all without monthly fees for basic services.
Learn more in our full Paypal review.
Pros & Cons
- Easy Setup and Use
- Trusted by Consumers
- All-in-One Solution
- No Monthly Fees (Basic)
- Transaction Fees Can Be High
- Not Great for High-Risk or Large Businesses
- Limited Customization on Basic Plan
- Withdrawal Limits and Fees:
Features
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- Electronic Signature
- In-Person Payments
- Mobile Payments
- Multiple Payment Gateways
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Processing Services Integration
- Recurring Billing
- Reporting/Analytics
- Mobile Credit card processing
- Contactless NFC
- Electronic Receipts
- Mobile Card Reader
- 3rd-Party Integrations
- iOS
- Android
- Cloud-Based
- On-place Installation
- Windows
- Mac
- Freemium
- Instore Sales
- Online Sales
- Mobile Sales
Pricing
$0
mo/
month
$30
mo/
month
$10
mo/
month
$14.99
mo/
month
$30
mo/
month

With over 20 years of experience, Merchant One is a trusted leader in credit card payment processing, serving industries such as retail, hospitality, and e-commerce. Offering state-of-the-art… Read more
With over 20 years of experience, Merchant One is a trusted leader in credit card payment processing, serving industries such as retail, hospitality, and e-commerce. Offering state-of-the-art technology and direct-to-source services, they ensure seamless transactions, competitive rates, and next-day funding. Known for their customer-centric approach, the merchant service provider streamlines payment solutions with no setup fees and flexible equipment leasing, making them a reliable partner for over 100,000 businesses. Their commitment to compliance and innovation guarantees businesses secure, efficient, and scalable solutions tailored to their unique needs. In this review, I'll cover the Merchant One pricing structure, features, performance, and more.
Learn more in our full Merchant One review.
Pros & Cons
- High Approval Rate Regardless of Credit
- Quick Setup
- Quick Access to Funds
- PCI Compliant
- Merchant One requires a three-year contract
- Services may be more expensive than competitors
Features
- ACH Payment Processing
- Billing & Invoicing
- Data Security
- Debit/Credit Card Processing
- Electronic Signature
- In-Person Payments
- Mobile Payments
- Multiple Payment Gateways
- Online payment processing
- PCI Compliance
- POS Integration
- Payment Fraud Prevention
- Payment Processing Services Integration
- Recurring Billing
- Reporting/Analytics
- Mobile Credit card processing
- Contactless NFC
- Electronic Receipts
- Mobile Card Reader
- 3rd-Party Integrations
- iOS
- Android
- Cloud-Based
- On-place Installation
- Windows
- Mac
- Monthly subscription
- Instore Sales
- Online Sales
- Mobile Sales
Pricing
$13.95
mo/
month
Why do businesses leave Stripe?
Most leave for one of four reasons, and each one points to a different replacement. Fund holds come first: Stripe's reserves FAQ says it can hold a fixed or rolling share of your balance when a business "presents an increased level of risk", including long delivery times or "unexplained surges in processing volume", and it publishes no standard hold length.
- Held payouts and closures: the account was approved instantly, then reviewed after the first big month. The fix is a processor that underwrites you before you go live.
- Restricted industries: Stripe's restricted list covers CBD, firearms, tobacco, telemedicine and nutraceuticals, and prohibits adult content, gambling and MLM. These businesses need a high-risk specialist, not a cheaper gateway.
- Flat-rate pricing at volume: 2.9% + 30¢ includes the card network's cost and Stripe's margin in one number. On interchange-plus you pay the network cost as-is plus a small, visible markup.
- No one to call: support is ticket-based. ISOs with a named rep are the answer, at the price of a contract.
Which Stripe alternative fits your situation?
Match your reason, not the star rating. Read the table as: your main problem with Stripe, the Sonary-reviewed processor that solves it, and the trade-off you accept.
Your problem with Stripe | Switch to | The trade-off |
|---|---|---|
Fees on every sale | Helcim | Low-risk industries only |
Low volume, a mix of in-person, online and keyed (phone) payments | Kurv | 24-month auto-renewing agreement |
Fees at $150K+/yr | Stax | $99-$199+ monthly subscription |
Industry restricted or account closed | PaymentCloud | Rates are quoted, not published |
Mostly in-person sales | Square | Online is pricier on the Free plan |
Buyers expect PayPal | PayPal | Higher checkout rate, freezes happen here too |
Want a human rep | Merchant One | 3-year contract |
Kurv: the no-monthly-fee pick for low-volume sellers?
Yes, especially if you key in card numbers or take phone orders. Kurv charges one flat 2.90% + 25¢ for both keyed and online payments, while Stripe adds 0.5% for manually entered cards, so a keyed payment there costs 3.4% + 30¢. On a $100 phone order, that is $3.15 on Kurv against $3.70 on Stripe. In person Kurv is 2.50% + 10¢, which beats Stripe Terminal (2.7% + 5¢) on any sale above $25. There is no monthly, setup, PCI or annual fee (Kurv pricing page), and the free Kurv Merchant App for iOS and Android takes Tap to Pay on iPhone, QR code payments, payment links and invoices, so a small seller needs no hardware to start. The one case where Kurv barely moves the needle is an online-only store: the savings there is 5¢ per transaction.
The catch is one Stripe does not have: a 24-month merchant agreement that renews automatically. Kurv lists a $0 early termination fee, but charges $395 for rented equipment you do not return, $25 per chargeback, and a monthly minimum of up to $25 in months you process less than that. Kurv also offers Zero Cost Processing, where the customer pays a 3.95% fee instead of you. Check your state's surcharging rules before you switch it on.
Kurv vs Stripe fees, side by side
Kurv is cheaper than Stripe on keyed cards, on online cards and on in-person sales above $25. Stripe is cheaper on small in-person tickets, on disputes and on flexibility. Rates are for US domestic Visa, Mastercard and Discover cards, from each company's pricing page.
Fee | Stripe | Kurv | Who wins |
|---|---|---|---|
Monthly fee | $0 | $0 | Tie |
Online card | 2.9% + 30¢ | 2.90% + 25¢ | Kurv, by 5¢ a sale |
Keyed card (phone orders) | 3.4% + 30¢ (2.9% + 0.5% surcharge) | 2.90% + 25¢ | Kurv, by 0.5% + 5¢ |
In person, card reader | 2.7% + 5¢ | 2.50% + 10¢ | Kurv above $25 a sale, Stripe below |
Tap to Pay on a phone | 2.7% + 5¢ + 10¢ per tap | 2.50% + 10¢ [KD: confirm Tap to Pay uses the swiped rate] | Kurv on every ticket size, if confirmed |
International cards | +1.5%, +1% more if currency converts | Not published | Ask Kurv |
Dispute | $15, plus $15 if you respond | $25, plus $25 per representment | Stripe |
Monthly minimum | None | $0 to $25, waived above $25 of activity | Stripe |
PCI fee | None | $0 to $79, waived once you complete the checklist | Tie if you file the checklist |
Payouts | Standard payouts free | Next business day, free | Tie |
Contract | None, leave any time | 24 months, renews automatically, $395 for unreturned rented equipment | Stripe |
What that means per sale:
Sale | Stripe fee | Kurv fee | Difference |
|---|---|---|---|
$100 keyed phone order | $3.70 | $3.15 | Kurv saves $0.55 |
$500 keyed invoice | $17.30 | $14.75 | Kurv saves $2.55 |
$100 online order | $3.20 | $3.15 | Kurv saves $0.05 |
$100 in person | $2.75 | $2.60 | Kurv saves $0.15 |
$25 in person | $0.73 | $0.73 | Tie |
$10 in person, card reader | $0.32 | $0.35 | Stripe saves $0.03 |
$10 on Tap to Pay | $0.42 | $0.35 [KD: if confirmed] | Kurv saves $0.07 |
For a mixed month, take a shop doing $10,000: $4,000 in person over 160 sales, $3,000 online over 60 orders and $3,000 keyed over 20 phone orders. Stripe charges $329 and Kurv $310, so Kurv saves $19 a month. The savings grow with the share of keyed cards (see the home-services example below, $160 a month). It disappears if your business is online-only or mostly small in-person tickets, and one fought chargeback on Kurv ($50) costs $20 more than on Stripe ($30).
Helcim: is interchange-plus actually cheaper than Stripe?
Yes, for most US cards - Helcim charges interchange + 0.50% + 25¢ online and interchange + 0.40% + 8¢ in person at up to $50K a month, with no monthly, setup or PCI fee (Helcim pricing page). On a $100 online sale that is 75¢ plus the card network's cost. Stripe charges $3.20 on the same sale, so Helcim wins whenever interchange on your card mix sits under 2.45%. Regulated debit cards sit far below that line, while some premium rewards cards bought online come close to it. Sonary's review flags the catch: Helcim only takes low-risk businesses.
Stax: when does a monthly fee beat a percentage?
Stax replaces the percentage markup with a subscription - $99 a month up to $150K a year in volume, $139 up to $250K, $199+ above that, plus 15¢ per online transaction and 0% markup on interchange (Stax pricing page). Sonary's review calls it "pricy for low-volume businesses", and the math agrees: the $99 only pays off once the markup you stop paying on every sale adds up to more than $99 a month. It is US-only.
PaymentCloud: what if Stripe banned your industry?
PaymentCloud is the Sonary-reviewed pick for merchants Stripe will not keep. It underwrites CBD, nutraceuticals, adult, firearms, subscription and travel businesses and quotes 24 hours to 5 days to go live. Rates are quoted per business, not published. Expect a rolling reserve at first - that is standard in high-risk, and it is agreed upfront instead of imposed after the fact.
Square: is it cheaper than Stripe?
Not online, Square's Free plan charges 3.3% + 30¢ for online payments, more than Stripe's 2.9% + 30¢, and matching Stripe's rate means the Plus plan at $49 per location per month (Square pricing page, 23 Sep 2026). Square wins in person: 2.6% + 15¢ on the Free plan, with hardware and a POS that work out of the box, no Terminal integration required.
PayPal and Merchant One: when do they make sense?
PayPal is a conversion choice, not a cost choice. PayPal Checkout runs 3.49% + a fixed fee and international adds 1.5%, but some buyers only finish checkout when they see the button. It also freezes accounts, so do not move to PayPal to escape holds. Merchant One suits owners who want 24/7 human support and high approval odds, and Sonary's review is clear on the price: a three-year contract.
Will switching from Stripe stop fund holds?
No - any processor can hold funds, including every option on this page. The difference is timing. Helcim, Stax and PaymentCloud review your business before approval, so a reserve is agreed at signup instead of appearing after your first strong month. Sonary's high-risk guide puts typical high-risk reserves at 5-10% of revenue for 90-180 days. Ask for the reserve terms in writing before you move volume.
Stripe holding funds? What actually happens to your money
Stripe can put a reserve on your account, which holds back part of your balance, and its support center says reserves typically last 30 to 90 days. There are three kinds:
- Fixed - a set percentage held until a set date.
- Rolling - a percentage of each payment held for a window, for example 30 days.
- Reserve plus balance transfer - your existing balance is held as well.
Closing the account does not free the money. Stripe says closing "doesn't release you from any liability related to your account balance", and once closed you can no longer refund customers or answer disputes. Merchants describe what that feels like: a practice manager reviewing Stripe in June 2026 wrote that Stripe "suddenly withheld and removed nearly $7,000 from our account", and another user review (April 2026) said the balance from an account closed in February 2025 was still not released more than a year later.
Support is not the gap people think it is. Every Stripe account gets 24x7 phone, email and chat. The gap is that frontline support cannot overrule a risk decision, so what you want from an alternative is a named rep or underwriter and reserve terms in writing.
Stripe alternatives for high-risk businesses: is yours on the restricted list?
Stripe publishes a restricted businesses list, and it changes over time. Adult content, gambling, debt relief and nutraceuticals with unsupported claims are prohibited. CBD, legal firearms, tobacco and vape, telemedicine, travel, crypto and lending need pre-approval. If that is you, a cheaper flat-rate processor is the wrong move - Helcim prohibits CBD, online vape sales and travel outright, which is stricter than Stripe. PaymentCloud is built for these verticals. Its own fee guide puts high-risk rates at 3.49% to 3.95% plus about 25¢, with reserves of 5% to 10% held for 90 to 180 days, so you get approved but you should still expect a reserve.
Stripe competitors compared: who each one fits
Who each one fits, who it does not, and what moving from Stripe really involves. Prices come from each vendor's own pricing page.
Alternative | Best for | Not for | What fixes the Stripe pain | Watch out for | Moving from Stripe |
|---|---|---|---|---|---|
Helcim | Low-risk US retail and online sellers doing $10K+ a month | CBD, vape, travel, gambling, adult (all prohibited) | Interchange-plus with a markup that falls as volume grows (in person: interchange + 0.40% + 8¢ under $50K a month), $0 monthly, $15 chargeback only if you lose | Recurring payments add 0.4% per transaction | Free card import, 5 to 10 business days. Cards only, rebuild subscriptions |
Kurv | Small in-person or online merchants looking for competitive rates and responsive, human customer support | Anyone who wants month-to-month | One flat 2.90% + 25¢ for keyed and online (Stripe: 3.4% + 30¢ keyed), 2.50% + 10¢ in person, no monthly fee, free iOS and Android app with Tap to Pay on iPhone and QR payments, optional cash-discount program where the customer pays 3.95% | 24-month agreement that auto-renews, $25 per chargeback plus $25 per representment, $395 for unreturned rental hardware | No documented card import, plan for customers re-entering cards |
Stax | Subscription, B2B and software businesses processing $150K+ a year | Low-volume or seasonal sellers, non-US businesses | $99, $139 or $199+ a month by annual volume, 0% markup on interchange, 8¢ in person and 15¢ online per transaction | The monthly fee still bills in a slow month, terminal protection is $19 a month | The only one here that documents importing Stripe card tokens plus subscription schedules, 7 to 14 business days after the file arrives. Stax Connect replaces Stripe Connect in about 45 days |
PaymentCloud | CBD, supplements, firearms, adult, travel, continuity billing | Low-risk sellers, who pay more here than at Helcim | High-risk underwriting, a dedicated account manager, live in 24 hours to 5 days, no long-term contract | 3.49% to 3.95% + about 25¢, reserves of 5% to 10% for 90 to 180 days | Runs on Authorize.net, NMI or USAePay. [KD: confirm card import] |
Square | In-person sellers who want POS, invoices and payroll together | Online-first sellers on the Free plan, restricted industries | No contract, signup to first payment in under an hour per Sonary's review | Online is 3.3% + 30¢ on Free, keyed is 3.5% + 15¢, holds happen here too | [KD: card import from Stripe unverified] |
PayPal | Online sellers whose buyers already pay with PayPal or Venmo | Anyone leaving Stripe over holds or fees | A checkout buyers trust, advanced card processing at 2.89% + 29¢ | PayPal Checkout is 3.49% + 49¢, holds up to 21 days and up to 180 days on a limited account | Run it beside Stripe rather than instead of it |
Merchant One | Established storefronts that want a named rep and equipment leasing | Anyone who wants an easy exit | Dedicated account manager, next-day funding | Sonary's review says a three-year contract, and published rates are qualified tiers, so non-qualified cards cost more | Ask for the contract before you sign |
Best Stripe alternatives by situation
The rates below are vendor list prices. The volumes are examples, so swap in your own statement.
1. A CBD or supplement store that Stripe just restricted - PaymentCloud. Stripe restricts CBD and prohibits nutraceuticals with unsupported claims, and Helcim prohibits both. Budget 3.49% to 3.95% per sale and a 5% to 10% reserve, and keep Stripe open until its own reserve clears.
2. A SaaS company on Stripe Billing doing $30,000 a month across 500 online payments - Stax.
Option | Math | Monthly cost |
|---|---|---|
Stripe + Billing | 2.9% × $30,000 + 500 × 30¢ + 0.7% Billing | $1,230, interchange included |
Stax | $199 + 500 × 15¢ | $274 + interchange |
Helcim | 0.50% × $30,000 + 500 × 25¢ + 0.4% recurring | $395 + interchange |
Stax wins on more than price: it is the only option here that imports your Stripe subscription schedules, so customers are not asked to re-enter cards. Interchange on your own card mix decides the real saving.
3. A coffee shop doing $20,000 a month in 800 card-present sales (about $25 each) - Kurv, or stay put.
Option | Math | Monthly cost |
|---|---|---|
Square Free | 2.6% + 15¢ | $640 |
Kurv | 2.50% + 10¢ | $580 |
Stripe Terminal | 2.7% + 5¢ | $580 |
Helcim | 0.40% + 8¢ markup | $144 + interchange |
Stripe Terminal already ties Kurv here, so fees alone are not a reason to leave. Kurv earns the switch with 24/7 US phone support and the cash-discount option, in exchange for a 24-month auto-renewing agreement.
4. A home-services business keying in 200 phone orders a month at about $150 each ($30,000) - Kurv.
Option | Math | Monthly cost |
|---|---|---|
Stripe (keyed) | 3.4% × $30,000 + 200 × 30¢ | $1,080 |
Kurv (keyed) | 2.90% × $30,000 + 200 × 25¢ | $920 |
Keyed cards are where Kurv's single online and keyed rate pays off: $160 a month here, with no monthly fee on top. The trade is still the 24-month auto-renewing agreement.
How do you leave Stripe without losing customers?
- Get approved at the new processor first. Stax will not import until your account is fully approved and active.
- Confirm the new processor can receive Stripe's card export. Stripe only sends it to a PCI DSS Level 1 processor that provides its attestation and a PGP key.
- Request the export through Stripe support (topic: migrations). You get customers, cards, emails and metadata in one encrypted file.
- Plan for what does not move: payment history, subscriptions, cards saved through Link and Connect accounts. Export subscriptions through the API or Dashboard and rebuild them, or pick Stax, which imports schedules.
- Download the balance summary report and your transaction CSVs before you touch the account.
- Do not close Stripe early. After closing you cannot refund or answer disputes, and the account cannot be reopened. Stop processing, keep it open until disputes age out and any reserve is paid.
- Map the new customer IDs in your database and add a card re-entry flow for the cards that fail to import.
Questions to ask before you sign
- Will you place a reserve on my account? What percentage, for how many days, and is it in writing?
- Is my industry on your prohibited or restricted list?
- Can you receive Stripe's card export, and do you import subscriptions and schedules or only cards?
- What is the contract term, does it auto-renew, and what do early exit and unreturned equipment cost?
- What does a chargeback cost, including representment?
- Is my rate interchange-plus, flat or tiered, and what do non-qualified cards cost?
- When my account is flagged, who do I call, and is that a named person?
See also
- best merchant services for small business
- best high-risk merchant accounts
- credit card processing fee calculator
- Stripe vs Square for online and in-person sales
- PayPal vs Stripe